Work Backwards From Your Life, Not Forward From a Rule: A Better Way to Find Your Retirement Number
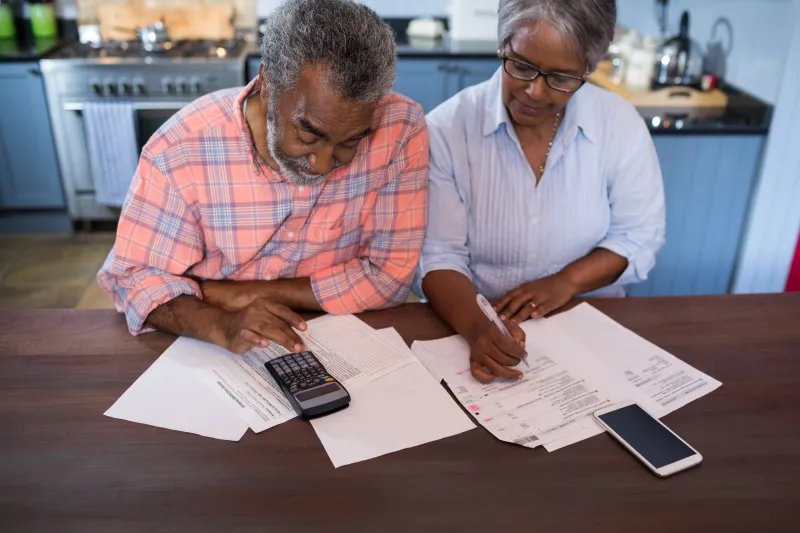
Photo: retiree reviewing finances at kitchen table with calculator and documents, via g.foolcdn.com
Ask ten financial advisors how much you need to retire and you'll hear some version of the same answer: a multiple of your salary, or 25 times your annual expenses, or 'it depends.' The first two are shorthand. The third is a dodge.
At Magna Invests, we think the question itself is malformed. 'How much do I need?' assumes your retirement target is a universal constant. It isn't. Your number is a function of your life — your spending, your tax situation, and above all your housing — and until you measure those inputs, any figure you're carrying around in your head is a guess wearing a suit.
The better approach is to work backwards. Start with the life you actually live, price it, and let the math tell you what the portfolio has to do.
Step One: Price the Life You Actually Live
Most people estimate their retirement spending by rounding their salary down. That's a mistake, because your paycheck is a poor proxy for your lifestyle. Gross income includes savings you'll stop making, taxes that will change shape, and commuting costs that will vanish.
Instead, build your number from the bottom up. Pull the last twelve months of bank and credit card statements and sort every expense into three buckets:
Essential spending. Housing, utilities, groceries, insurance, healthcare premiums, transportation. This is your floor — the spending that continues no matter what markets do.
Lifestyle spending. Travel, dining, hobbies, gifts, that second streaming service you forgot about. This bucket is flexible; it's where you'll cut in a bear market without changing your life.
Legacy and lump-sum spending. Home repairs, helping adult children, vehicle replacements, grandkids. Retirees consistently underestimate this bucket because it arrives in irregular, lumpy bursts rather than monthly installments.
Use this worksheet to translate your spending into a target:
| Worksheet: Your Annual Retirement Budget |
|---|
| Essential annual spending: $________ |
| Lifestyle annual spending: $________ |
| Lump-sum/legacy reserve (add ~5% of essentials): $________ |
| Gross annual need: $________ |
Step Two: Subtract What Disappears, Add What Appears
Retirement doesn't just end a paycheck — it rewrites your cash flow. Work through the adjustments:
Gone: payroll taxes on the income you no longer earn, retirement contributions (you're now withdrawing, not saving), commuting costs, payroll-deducted life insurance you may no longer need.
Arriving: Medicare premiums (before 65, ACA marketplace coverage — potentially the single largest line item for early retirees), supplemental insurance, and often a startling amount of discretionary travel in the first active decade.
Transformed: your tax bill. This is where most back-of-envelope math falls apart. A married couple filing jointly with $95,000 of retirement income drawn largely from Roth and taxable accounts may owe dramatically less in federal tax than their working-bracket intuition suggests. Another couple drawing the same amount from a traditional 401(k) may face required minimum distributions that push them into a higher bracket than they ever occupied while working.
The lesson: your number isn't just a spending number. It's a gross withdrawal number — the amount you must pull from accounts to net the spending you want after taxes.
Step Three: Apply the Withdrawal Logic
With your gross annual need in hand, the classic 4% guideline gives you a first-pass target: multiply your gross annual need by 25. But treat that as a starting point, not a verdict. Retiring at 62 with a 30-plus-year horizon may warrant a more conservative 3.5% initial rate. Retiring at 70 with Social Security covering a large share of essentials can justify more flexibility.
Two Portfolios, Two Numbers: A Case Study
Consider two households, each with $1.2 million saved at age 63.
Household A — the mortgage-free downsizer. They sold the family home in Ohio, bought a smaller place in cash, and spend $4,800/month total. After taxes, their gross withdrawal need is roughly $68,000. At a 4% rate, their number is about $1.7 million — they're close, and Social Security at 67 closes the gap entirely.
Household B — the high-cost holdouts. Same $1.2 million, but they're carrying a $2,600/month mortgage on a coastal California home, plus property taxes and insurance that have climbed sharply. Their gross need exceeds $115,000. Their number at 4% is roughly $2.9 million — nearly double Household A's, from an identical balance.
Same portfolio. Same age. Radically different retirement readiness. The difference isn't investment skill. It's housing, taxes, and spending — the inputs almost nobody calculates before panicking about market returns.
Run Your Own Mirror
Before you blame the market for a number that feels out of reach, hold up the mirror:
- Total twelve months of actual spending by bucket.
- Add expected healthcare costs and subtract payroll-era expenses that end.
- Estimate taxes on your likely withdrawal mix (traditional, Roth, taxable).
- Multiply your gross annual need by 25 — then stress it at 3.5%.
- Compare the result to your current balance and ask which input — not which fund — moves the number most.
For most households, the answer is housing or the tax character of their accounts, not their stock picks. That's good news: those are levers you control years before your last paycheck. Run the mirror now, while there's still time to adjust the inputs — because your retirement number was never really about the market. It's about the life you're planning to fund.